Signal as Collateral: The Quiet Repricing of Farmland in the Age of Connectivity
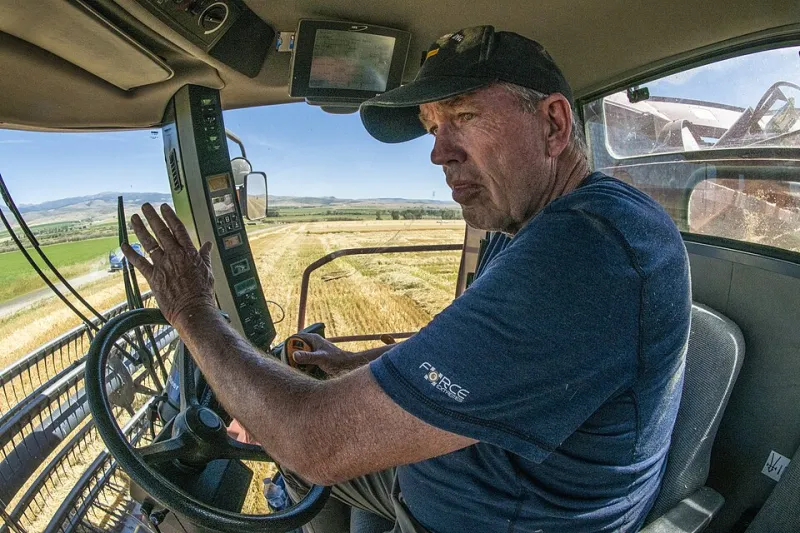
Photo: USDAgov, Public domain, via Wikimedia Commons
For most of the last century, a parcel of Midwest farmland was judged by three things: the dirt, the water, and the road that served it. A fourth factor has now entered the appraisal file, and it does not appear on any soil survey — the strength of the cellular signal standing at the end of the field.
Rural appraisers and land brokers across the Corn Belt and High Plains report that connectivity is no longer a footnote in a sales pitch. It is a line item. And for growers who run guidance systems, telemetry-driven irrigation, and cloud-based yield monitors, that line item can swing a bid by real money.
When Bars Become Basis Points
The mechanics are straightforward even if the industry rarely says them out loud. A farm that can move data — upload yield maps from the combine, pull weather telemetry from the pivot, run remote diagnostics on the planter — is a farm that operates with less labor and less guesswork. A comparable farm two counties over, sitting in a coverage shadow, forces its operator to drive thirty miles to upload a season's data or to rely on hardware workarounds that add cost and complexity.
Appraisers describe the effect as a widening spread between 'connected acreage' and everything else. It is rarely a headline adjustment on the appraisal form. Instead, it shows up in days on market, in the number of qualified bidders at auction, and in the willingness of tech-forward operators to stretch on price. A farm with solid LTE or fiber at the shop simply has a larger buyer pool, and larger buyer pools clear higher.
Brokers in areas where rural broadband buildouts have landed report the pattern anecdotally but consistently: parcels near new fiber trunk lines or newly towered corridors draw attention from a class of buyer that did not exist a decade ago — the part-time operator, the investor-landlord, the expanding neighbor whose entire operation runs on a tablet.
The Regions Gaining Ground
The geography of this repricing is not uniform. Counties within range of ongoing fiber expansion — often along interstate corridors and near regional hubs in Iowa, Nebraska, Indiana, and the Dakotas — are capturing a premium. Areas served by newly licensed fixed-wireless providers have seen similar movement, particularly in rolling terrain where line-of-sight wireless can reach ground that towers alone cannot.
Conversely, some of the most productive ground in the country sits at a relative discount. Deep-soiled river bottoms and remote sections of the Plains can be agronomically superior and digitally stranded at the same time. Satellite-based services have narrowed the gap, but latency, data caps, and weather sensitivity still matter to an operator deciding between two farms at auction.
What Buyers Should Verify Before the Handshake
A coverage map on a carrier's website is a marketing document, not a survey. Buyers evaluating weak-signal ground should treat connectivity diligence with the same rigor they apply to tile records and water rights.
Run a physical speed test, not a map check. Stand at the homestead, at the shop, and at the far corner of the parcel with the actual devices you intend to use. Coverage maps interpolate; they do not measure.
Ask what the neighbors run. An operator farming the adjoining section can tell you in five minutes which carrier holds a signal and which one drops it every time the soybeans get tall.
Price the workaround. If the ground needs a signal booster, a fixed-wireless hop, or a satellite terminal to support your precision stack, get the quote before you bid. A $4,000 connectivity retrofit is a rounding error on a quarter section; a $40,000 tower lease negotiation is not.
Check the upgrade horizon. County broadband plans, USDA ReConnect awards, and state grant programs are public record. Knowing whether fiber is scheduled, funded, or merely hoped for changes the calculus between a permanent discount and a temporary one.
The Seller's Side of the Ledger
Landowners preparing to sell have their own homework. A documented connectivity profile — measured speeds at multiple points, installed fiber or fixed-wireless service, proximity to planned builds — is cheap to assemble and can materially widen the buyer pool. In a market where the marginal bidder often sets the price, giving that marginal bidder a reason to bid is worth more than any sign on the road.
The broader implication is one the industry is still absorbing: digital infrastructure is becoming a land characteristic, as durable in its effect as drainage or soil class. The Wi-Fi fence is not a metaphor for much longer. It is a boundary line on the map, and it is already moving the numbers.